Truck Finance with No Deposit: What Lenders Really Look For
Yes, you can buy a truck with no deposit, but not everyone qualifies, and it isn’t always the cheapest route. This guide explains when zero-deposit truck finance works, what it costs, and what to do if a lender wants money down. When you’re ready, our truck finance broker team can check your options.
When lenders approve no deposit
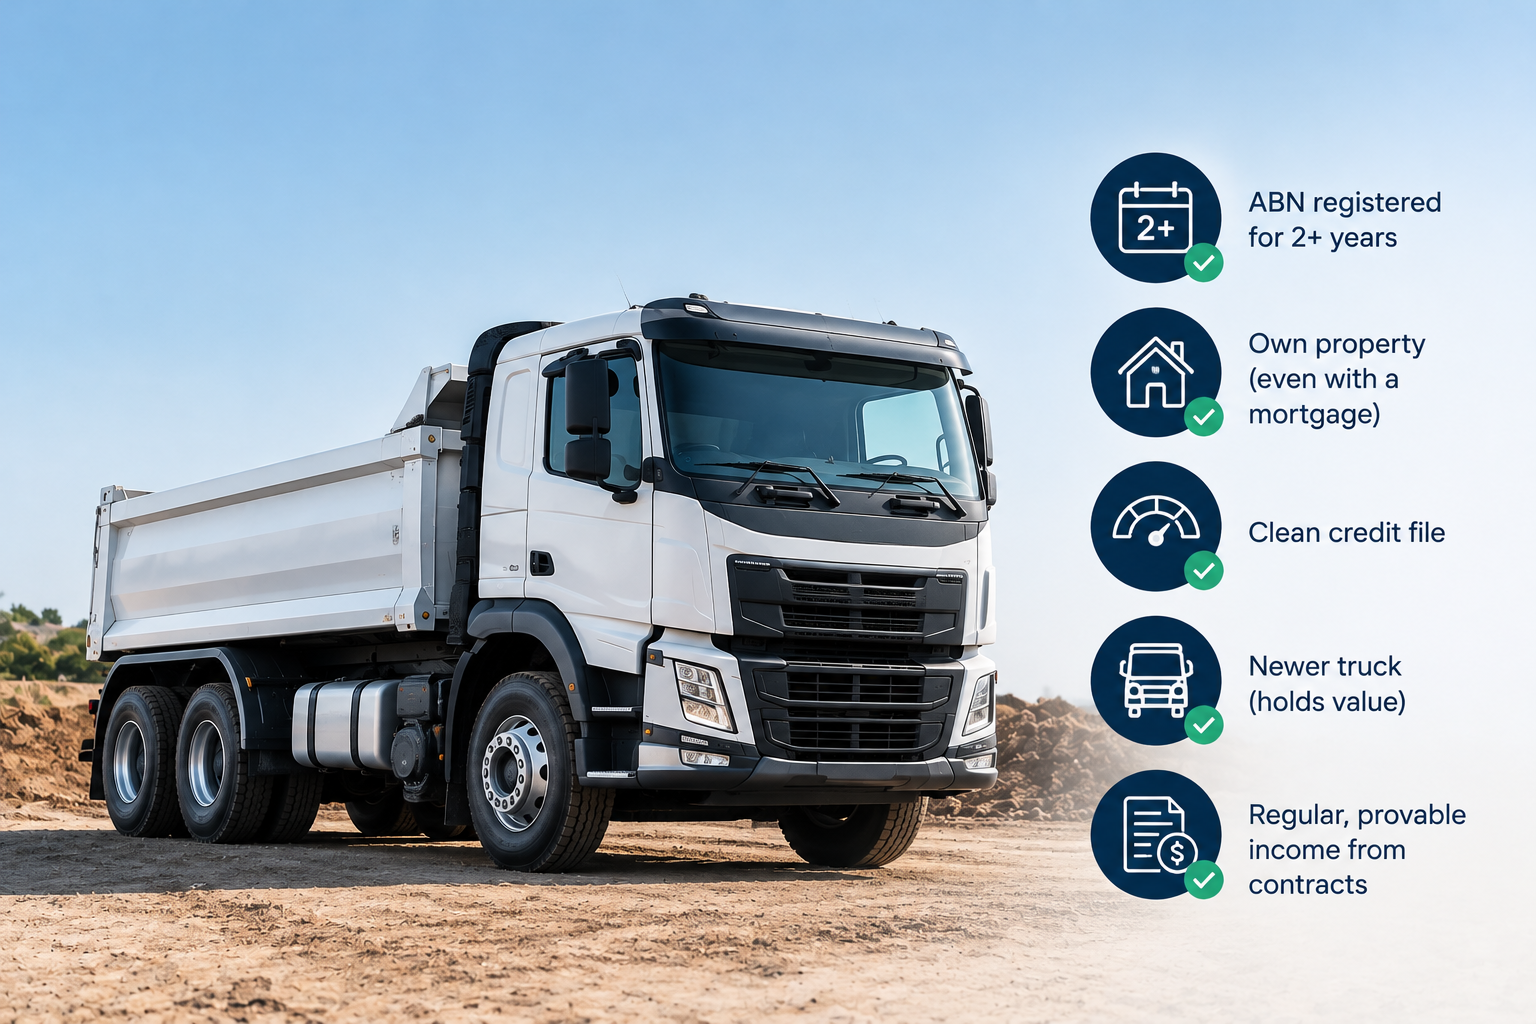
Lenders are most comfortable funding 100% of the price when several of these line up:
- your ABN has been registered for a while, often 2 years or more
- you own property, even with a mortgage on it
- your credit file is clean
- the truck is newer, so it holds value against the loan
- you have regular, provable income from contracts
The fewer of these you tick, the more likely a lender asks for a deposit.
What no deposit costs you
Borrowing the full price means a bigger loan, so higher repayments and more interest over the term. The rate may also be higher, because the lender’s money is at more risk. Worked example (illustrative only): on a $150,000 truck over 5 years at an assumed rate of 9.5% p.a., borrowing the full amount costs roughly $3,150 a month and about $39,000 in interest. Put down a 10% deposit ($15,000) and the loan drops to $135,000, with repayments of around $2,835 a month and about $35,100 in interest. Your actual rate depends on your profile, the truck and the lender.
Options if you don’t have cash
- Trade-in. The equity in your current truck can serve as the deposit.
- GST on a chattel mortgage. If you’re registered for GST, you may be able to claim the GST on the purchase in your next BAS. Some operators use that refund to pay down the loan early. Check with your accountant first.
- A guarantor or property security. This can tip a borderline application to approval.
A cheaper first truck. Building a repayment history now makes the next truck easier.
No Deposit Truck Finance: frequently asked questions
Can I get no deposit truck finance with a new ABN?
It’s harder. Most lenders that approve zero-deposit truck loans want an ABN that has been active for at least 12 to 24 months, a clean credit file and some history of paying off a vehicle or equipment loan. With a newer ABN, a deposit or a trade-in usually makes the difference.
Does no deposit mean higher repayments?
Yes. You’re borrowing the full price, so repayments and total interest are higher than if you put money down. Some lenders also price no-deposit loans slightly higher to cover the extra risk.
Can I use my trade-in instead of a cash deposit?
Usually, yes. Equity in a truck you already own can act as your deposit, which can improve both your approval chances and the rate you’re offered.
Can the GST be included in the loan?
Many lenders will finance the GST on a commercial vehicle. If you’re registered for GST you can usually claim it back on your next BAS and pay that amount off the loan. Check the details with your accountant.
Related finance options
Not quite the right fit? These pages cover options that often suit people in a similar position:
Prefer to talk it through? Book a free consultation or call +61 405 142 021.