Home Loan Refinance Broker: Is Your Bank Still Earning Your Loyalty?
Banks often save their sharpest rates for new customers. If you took out your loan a few years ago and haven’t asked for a better deal since, there’s a fair chance you’re paying more than someone walking in the door today. A refinance broker checks that for you, and if switching makes sense, does the legwork.
We compare home loans from the lenders on our panel. As mortgage brokers, we’re legally required to act in your best interests, so if staying put is the better option, we’ll tell you.
Five good reasons to refinance
- A lower rate. Even a small cut, on a large balance over many years, adds up.
- Coming off a fixed rate. When a fixed term ends, many loans roll onto a higher variable rate. It’s the most common moment to review.
- Better features. An offset account, free extra repayments, or a split between fixed and variable.
- Accessing equity. Releasing equity for a renovation, an investment deposit or a business purpose.
Consolidating debts. Rolling car loans or credit cards into your mortgage at a lower rate. Be careful: stretching a 5-year debt over 25 years can cost more overall. See debt consolidation loan broker.
The costs of switching
Refinancing isn’t free, and a good broker puts the costs on the table first:
- Discharge fee from your current lender
- Break costs if you’re leaving a fixed rate early, which can be large when rates have fallen
- Application or settlement fees with the new lender (often waived)
- Government registration fees for discharging and registering the mortgage
- Lenders mortgage insurance (LMI) if you owe more than 80% of the property’s value
We work out your break-even point: how many months of lower repayments it takes to recover these costs. If you plan to sell before then, refinancing may not be worth it.
Cashback offers
Some lenders offer a cash payment for switching. It’s tempting, but judge the loan on its rate and features over the years you’ll hold it, not on the cheque at settlement.
How it works with us
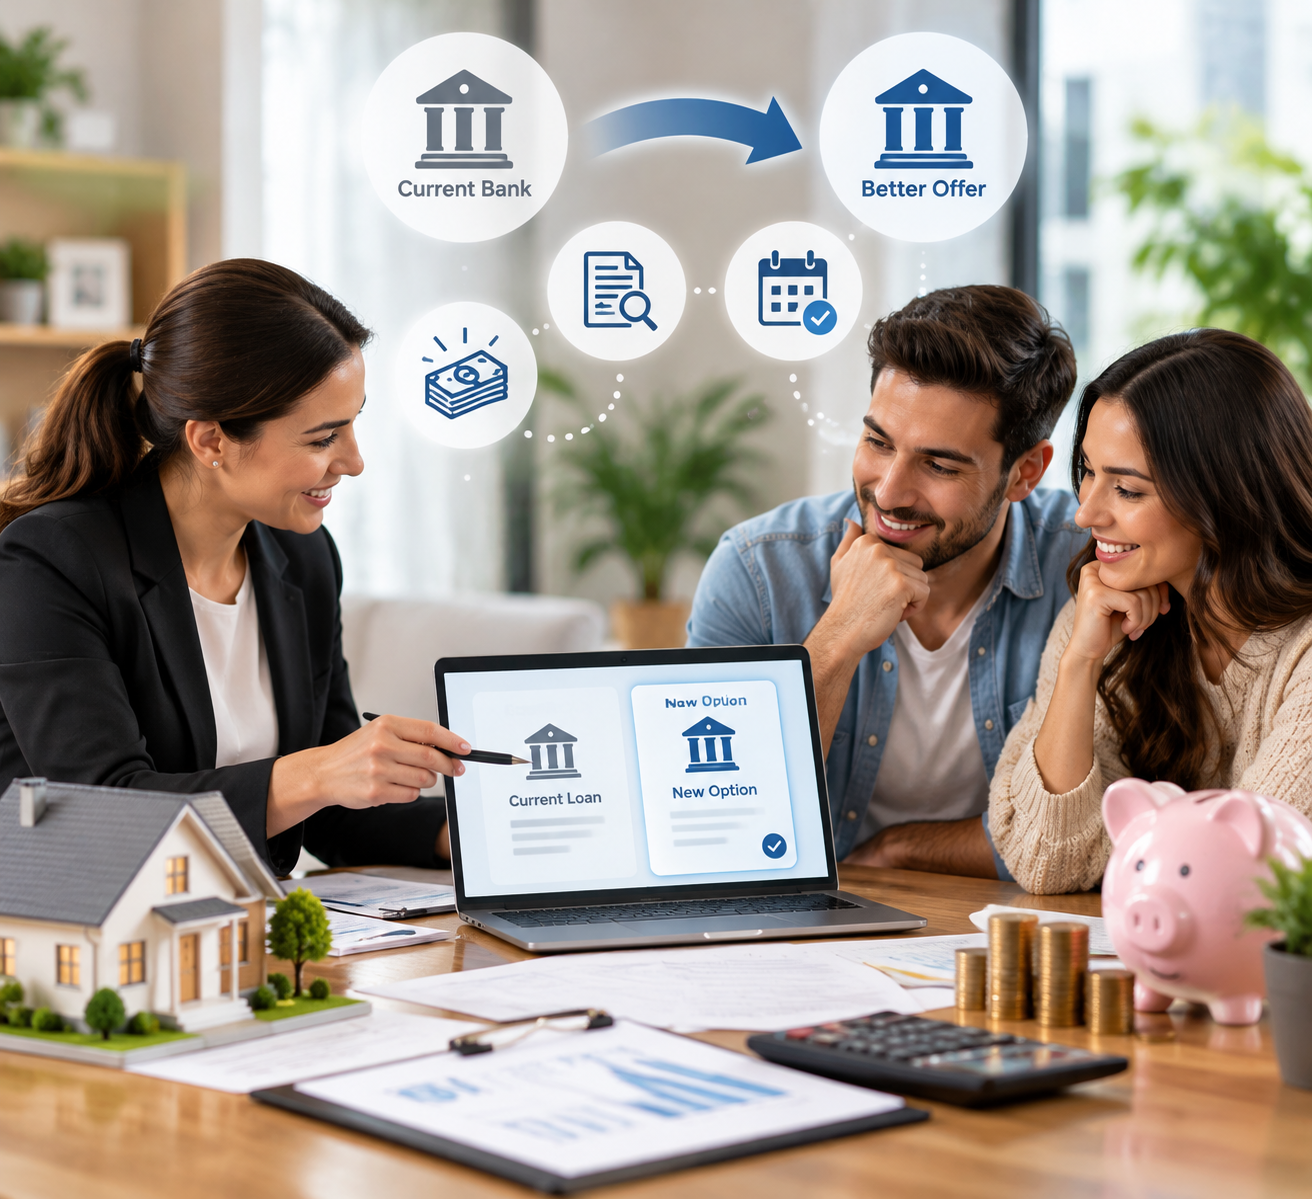
- Loan review. Send us your latest loan statement. We compare it against current offers on our panel.
- If switching is worthwhile, we show you the options side by side, including the comparison rate and all fees.
- We lodge with one lender, arrange the valuation and keep you updated.
- The new lender pays out the old one. You just start making repayments to the new lender.
- Annual check-in. We review your rate every year so you don’t drift back onto a stale deal.
Can’t you just ask your bank?
You should, and sometimes that’s enough. Your bank may cut your rate if you show them a competing offer. We can give you that offer in writing. If they match it, you’ve saved without switching.
Home Loan Refinance: frequently asked questions
How often can I refinance?
There’s no legal limit, but each switch has costs and appears on your credit file. Once every few years, or when a fixed rate ends, is typical.
Will refinancing hurt my credit score?
A new application adds an enquiry. One well-chosen application has little effect; several in a row can. That’s one reason to use a broker.
How long does it take?
Usually two to four weeks from application to settlement, depending on the new lender and how quickly your current lender releases the mortgage.
Does a broker cost me anything?
Brokers are usually paid a commission by the lender when your loan settles. We’ll explain exactly how we’re paid, and any fees, in our credit guide before we help you apply.
Related finance options
Not quite the right fit? These pages cover options that often suit people in a similar position:
Prefer to talk it through? Book a free consultation or call +61 405 142 021.