Debt Consolidation Loans: One Repayment, Done Properly
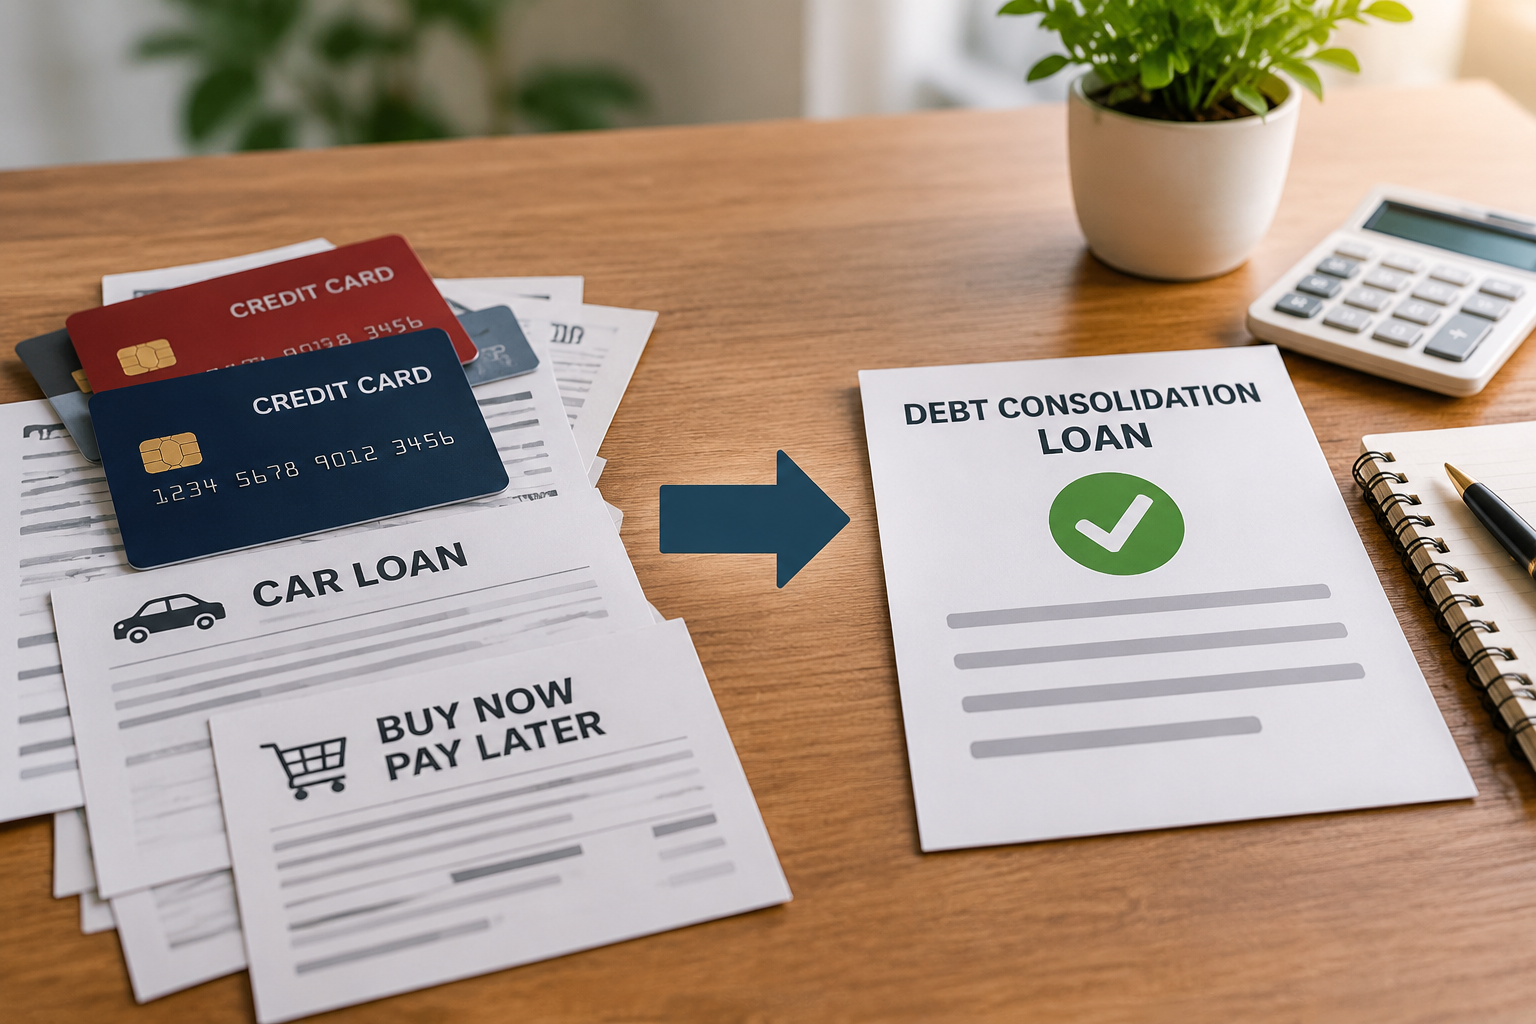
When you’ve got two credit cards, a car loan and a buy-now-pay-later account all due on different days, it’s easy to lose track and hard to get ahead. A debt consolidation loan pays them off and replaces them with one loan and one repayment. Done well, it can lower your interest and give you a clear end date. Done badly, it just moves the debt around. We’ll help you work out which it would be. Part of our personal loan broker service.
When consolidation makes sense
- The new loan’s comparison rate is lower than the average rate on your current debts
- The term is no longer than you need, so you don’t pay interest for years longer
- You’re ready to close or cut the limits on the cards you pay off
Your repayments are manageable now, and you want a clearer plan
When it doesn't
If you’re already missing payments, or the new repayment would still be a stretch, a new loan may not be the answer. Free, confidential help is available from a financial counsellor through the National Debt Helpline on 1800 007 007. We’d rather you got the right help than the wrong loan.
Using your home loan instead
Homeowners can sometimes roll debts into their mortgage at a much lower rate. The trap is time: spreading a 3-year car loan over 25 years can mean paying more interest overall, even at a lower rate. If you go this way, plan to make extra repayments. See home loan refinance broker.
What we’ll ask for
A list of each debt with its balance, rate and repayment, recent payslips or proof of income, and bank statements. Be upfront about everything; a lender will see it on your credit file anyway.
Debt Consolidation Loan: frequently asked questions
Will consolidation improve my credit score?
Over time, making one repayment on time and reducing your total credit limits can help. The application itself adds an enquiry.
Can I consolidate with bad credit?
Sometimes, with specialist lenders, but rates are higher. We’ll tell you honestly whether it would leave you better off.
Should I close my credit cards?
In most cases, yes, or at least lower the limit. Otherwise it’s easy to end up with the new loan and new card debt.
Related finance options
Not quite the right fit? These pages cover options that often suit people in a similar position:
Prefer to talk it through? Book a free consultation or call +61 405 142 021.