Small Business Overdrafts and Lines of Credit
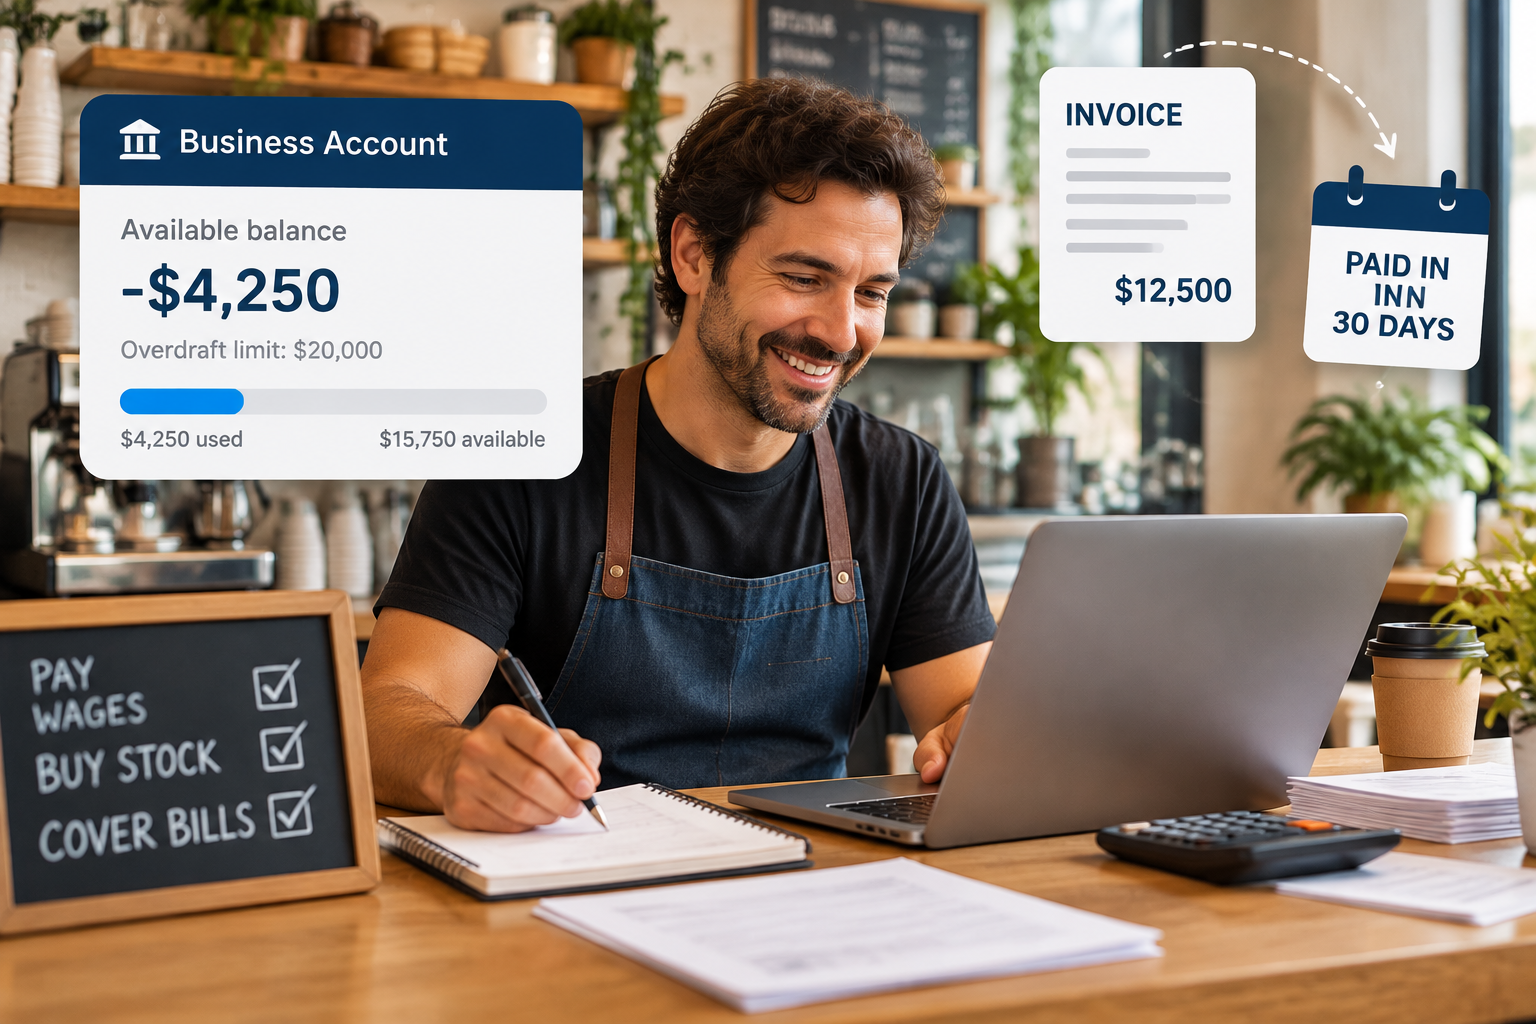
Most small businesses don’t run out of profit; they run out of cash while waiting to be paid. An overdraft or line of credit is a buffer for those weeks: wages are due Friday, the big invoice lands in 30 days, and the gap in between gets covered. We help small businesses find the right facility, at the right limit, from a lender that suits how they trade.
How a business overdraft works
An overdraft is linked to your business transaction account. You get an approved limit and can go below zero up to that limit. You pay interest only on the amount you’re overdrawn, for the days you’re overdrawn. Most lenders also charge a fee on the limit itself, whether you use it or not, so a bigger limit than you need isn’t free.
Business line of credit
A line of credit works similarly but sits as a separate account. You draw funds when you need them, repay them when cash comes in, and draw again. Some lenders’ lines of credit come with a minimum monthly repayment, which can suit businesses that want more discipline than an overdraft gives.
As a business line of credit broker, we compare banks and non-bank lenders on limit, rate, fees and how fast funds are available. Non-bank lines of credit are often quicker to set up and may not need property security, but usually cost more.
Overdraft or line of credit: which suits your business?
Feature | Overdraft | Line of credit | Working capital loan |
How you draw | Through your transaction account | From a separate account, as needed | Lump sum up front |
Interest | On the overdrawn balance | On the drawn balance | On the full loan |
Repayments | Flexible | Flexible or minimum monthly | Fixed schedule |
Best for | Day-to-day ups and downs | Recurring gaps, e.g. invoice timing | A one-off need, e.g. stock or a contract |
Business Overdraft & Line of Credit: frequently asked questions
Can sole traders get an overdraft?
Yes. Many lenders offer overdrafts and lines of credit to sole traders with enough trading history.
How much can I get?
Unsecured limits are typically linked to your turnover; secured limits to the value of the security. We can tell you what limit you’re likely to get once we’ve seen your figures.
Are there fees if I don't use it?
Often, yes: a limit or line fee. Ask for the full fee schedule.
Can a new business get one?
It’s harder. Some lenders consider businesses trading for 6 months; most want longer.
Related finance options
Not quite the right fit? These pages cover options that often suit people in a similar position:
Prefer to talk it through? Book a free consultation or call +61 405 142 021.